Greg Cordell USSSA Director Activity Profile
Hidden Valley — Integrity of the Game | Oklahoma USSSA Research 2001–2026

Greg Cordell — USSSA Director Activity Profile

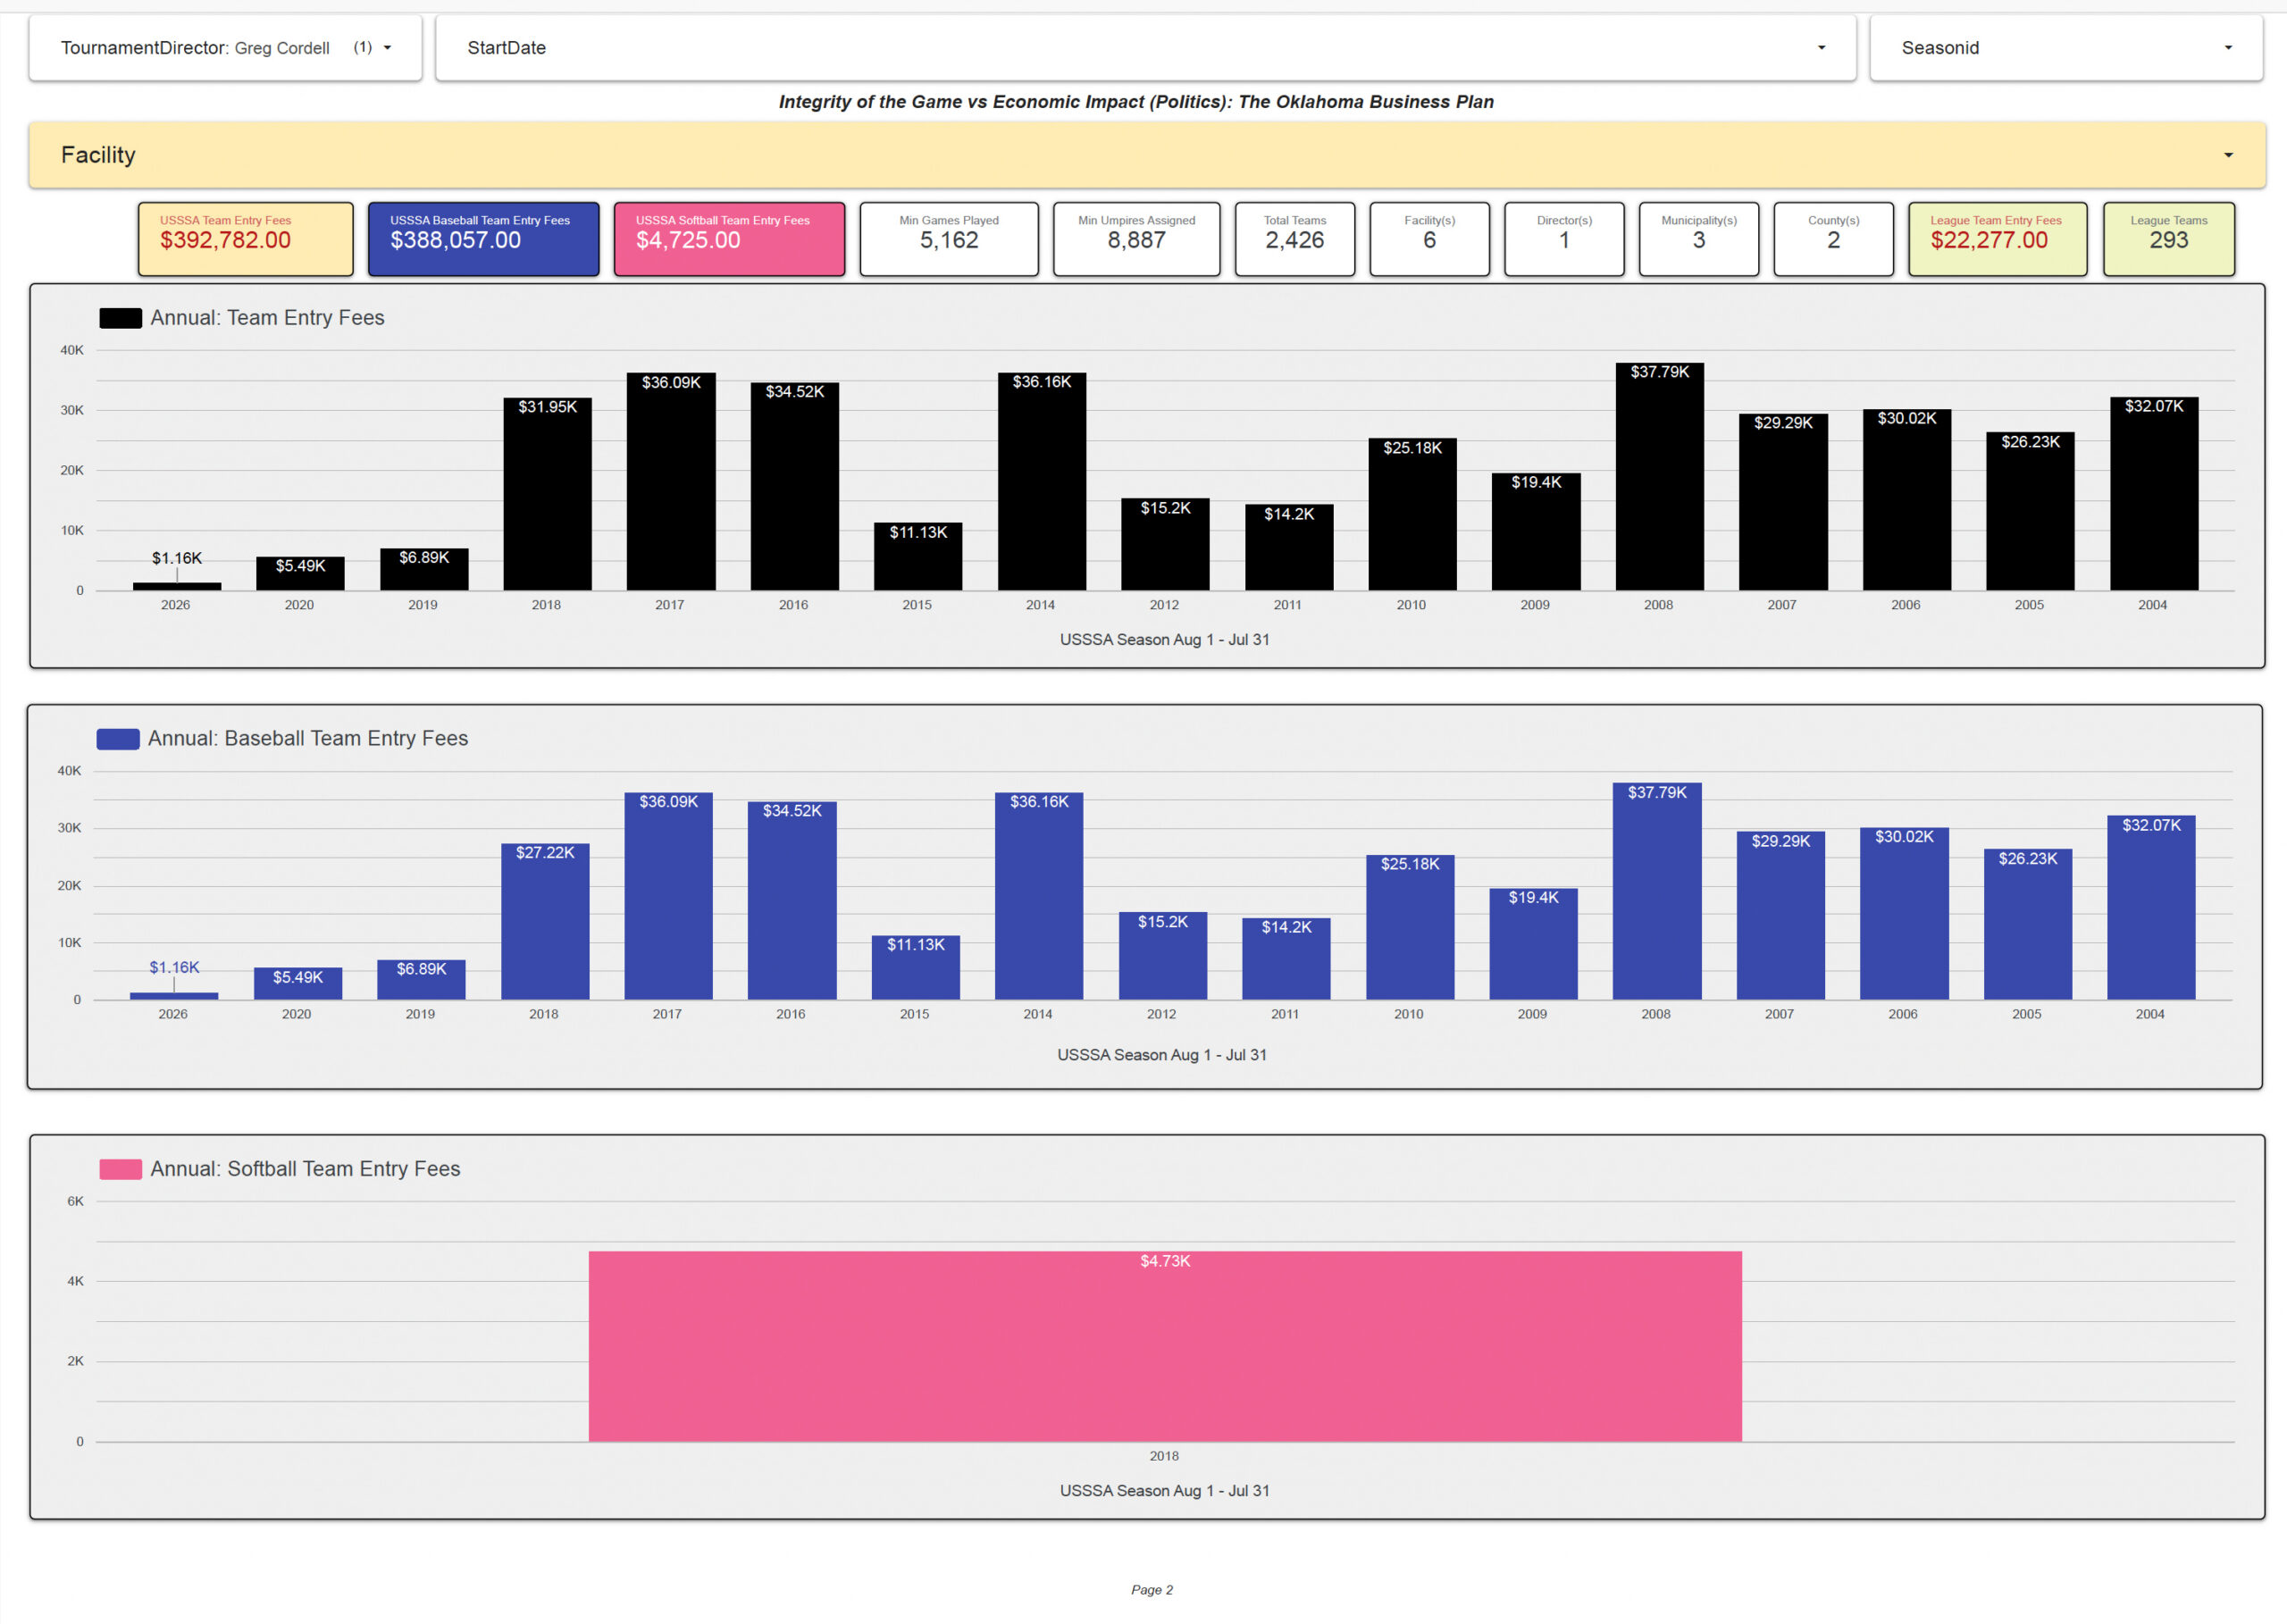
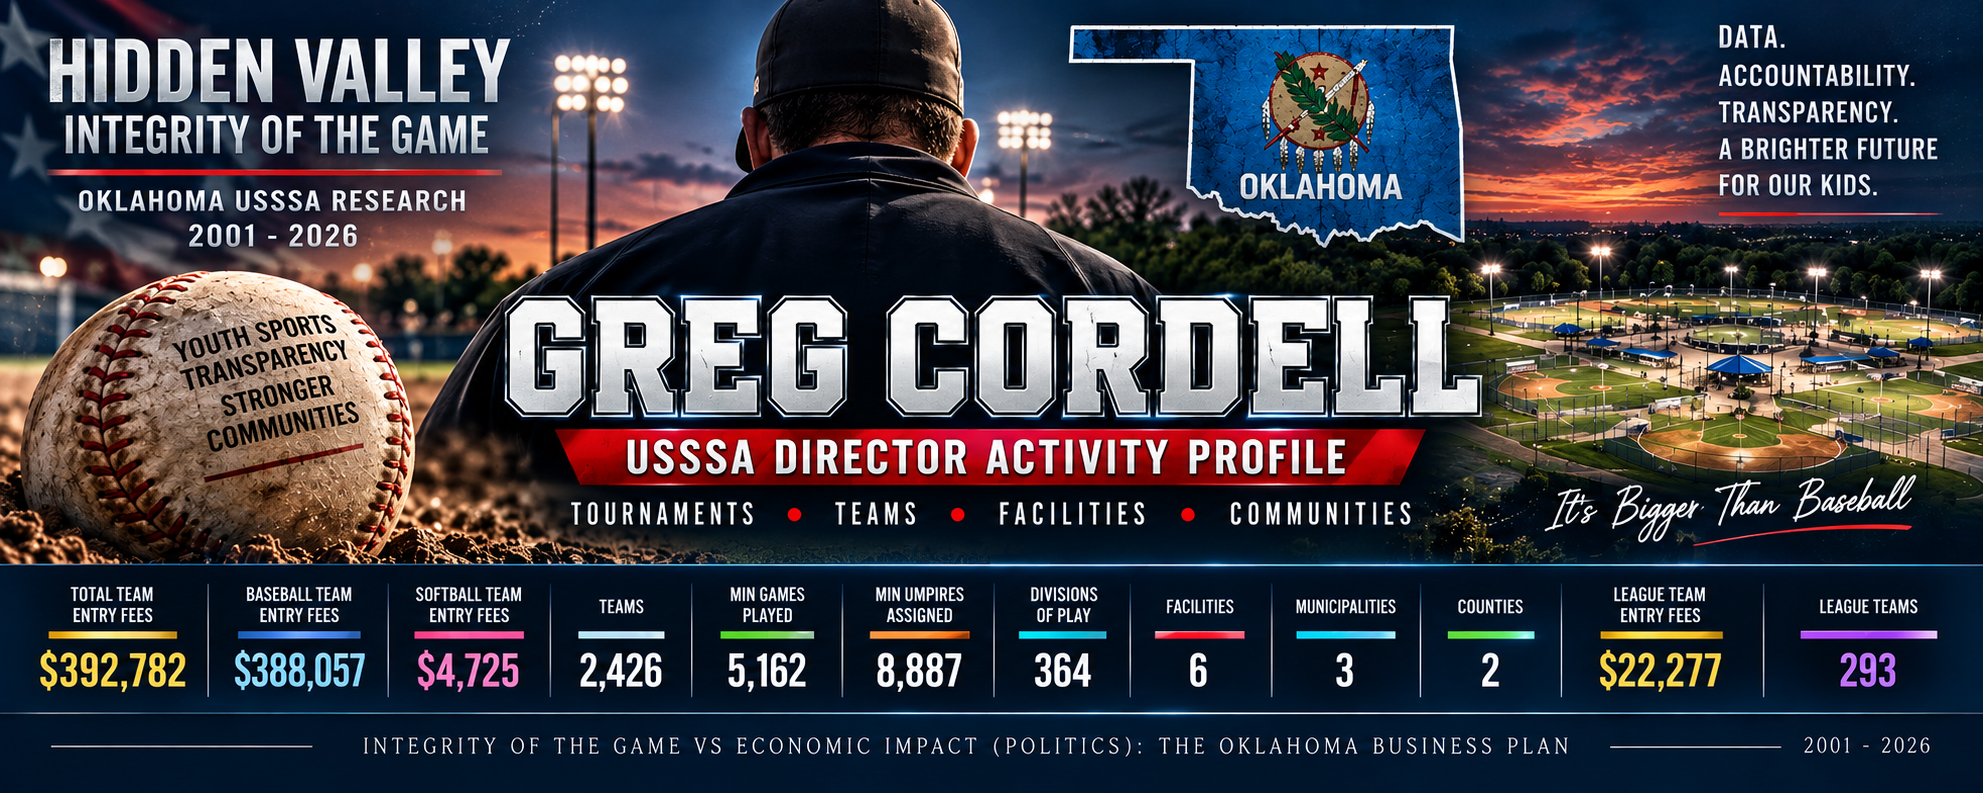
The updated research profile documents tournament activity associated with Greg Cordell across the Oklahoma USSSA research dataset, including calculated team entry fees, teams, minimum games, minimum officiating assignments, divisions, facilities, municipalities and counties.

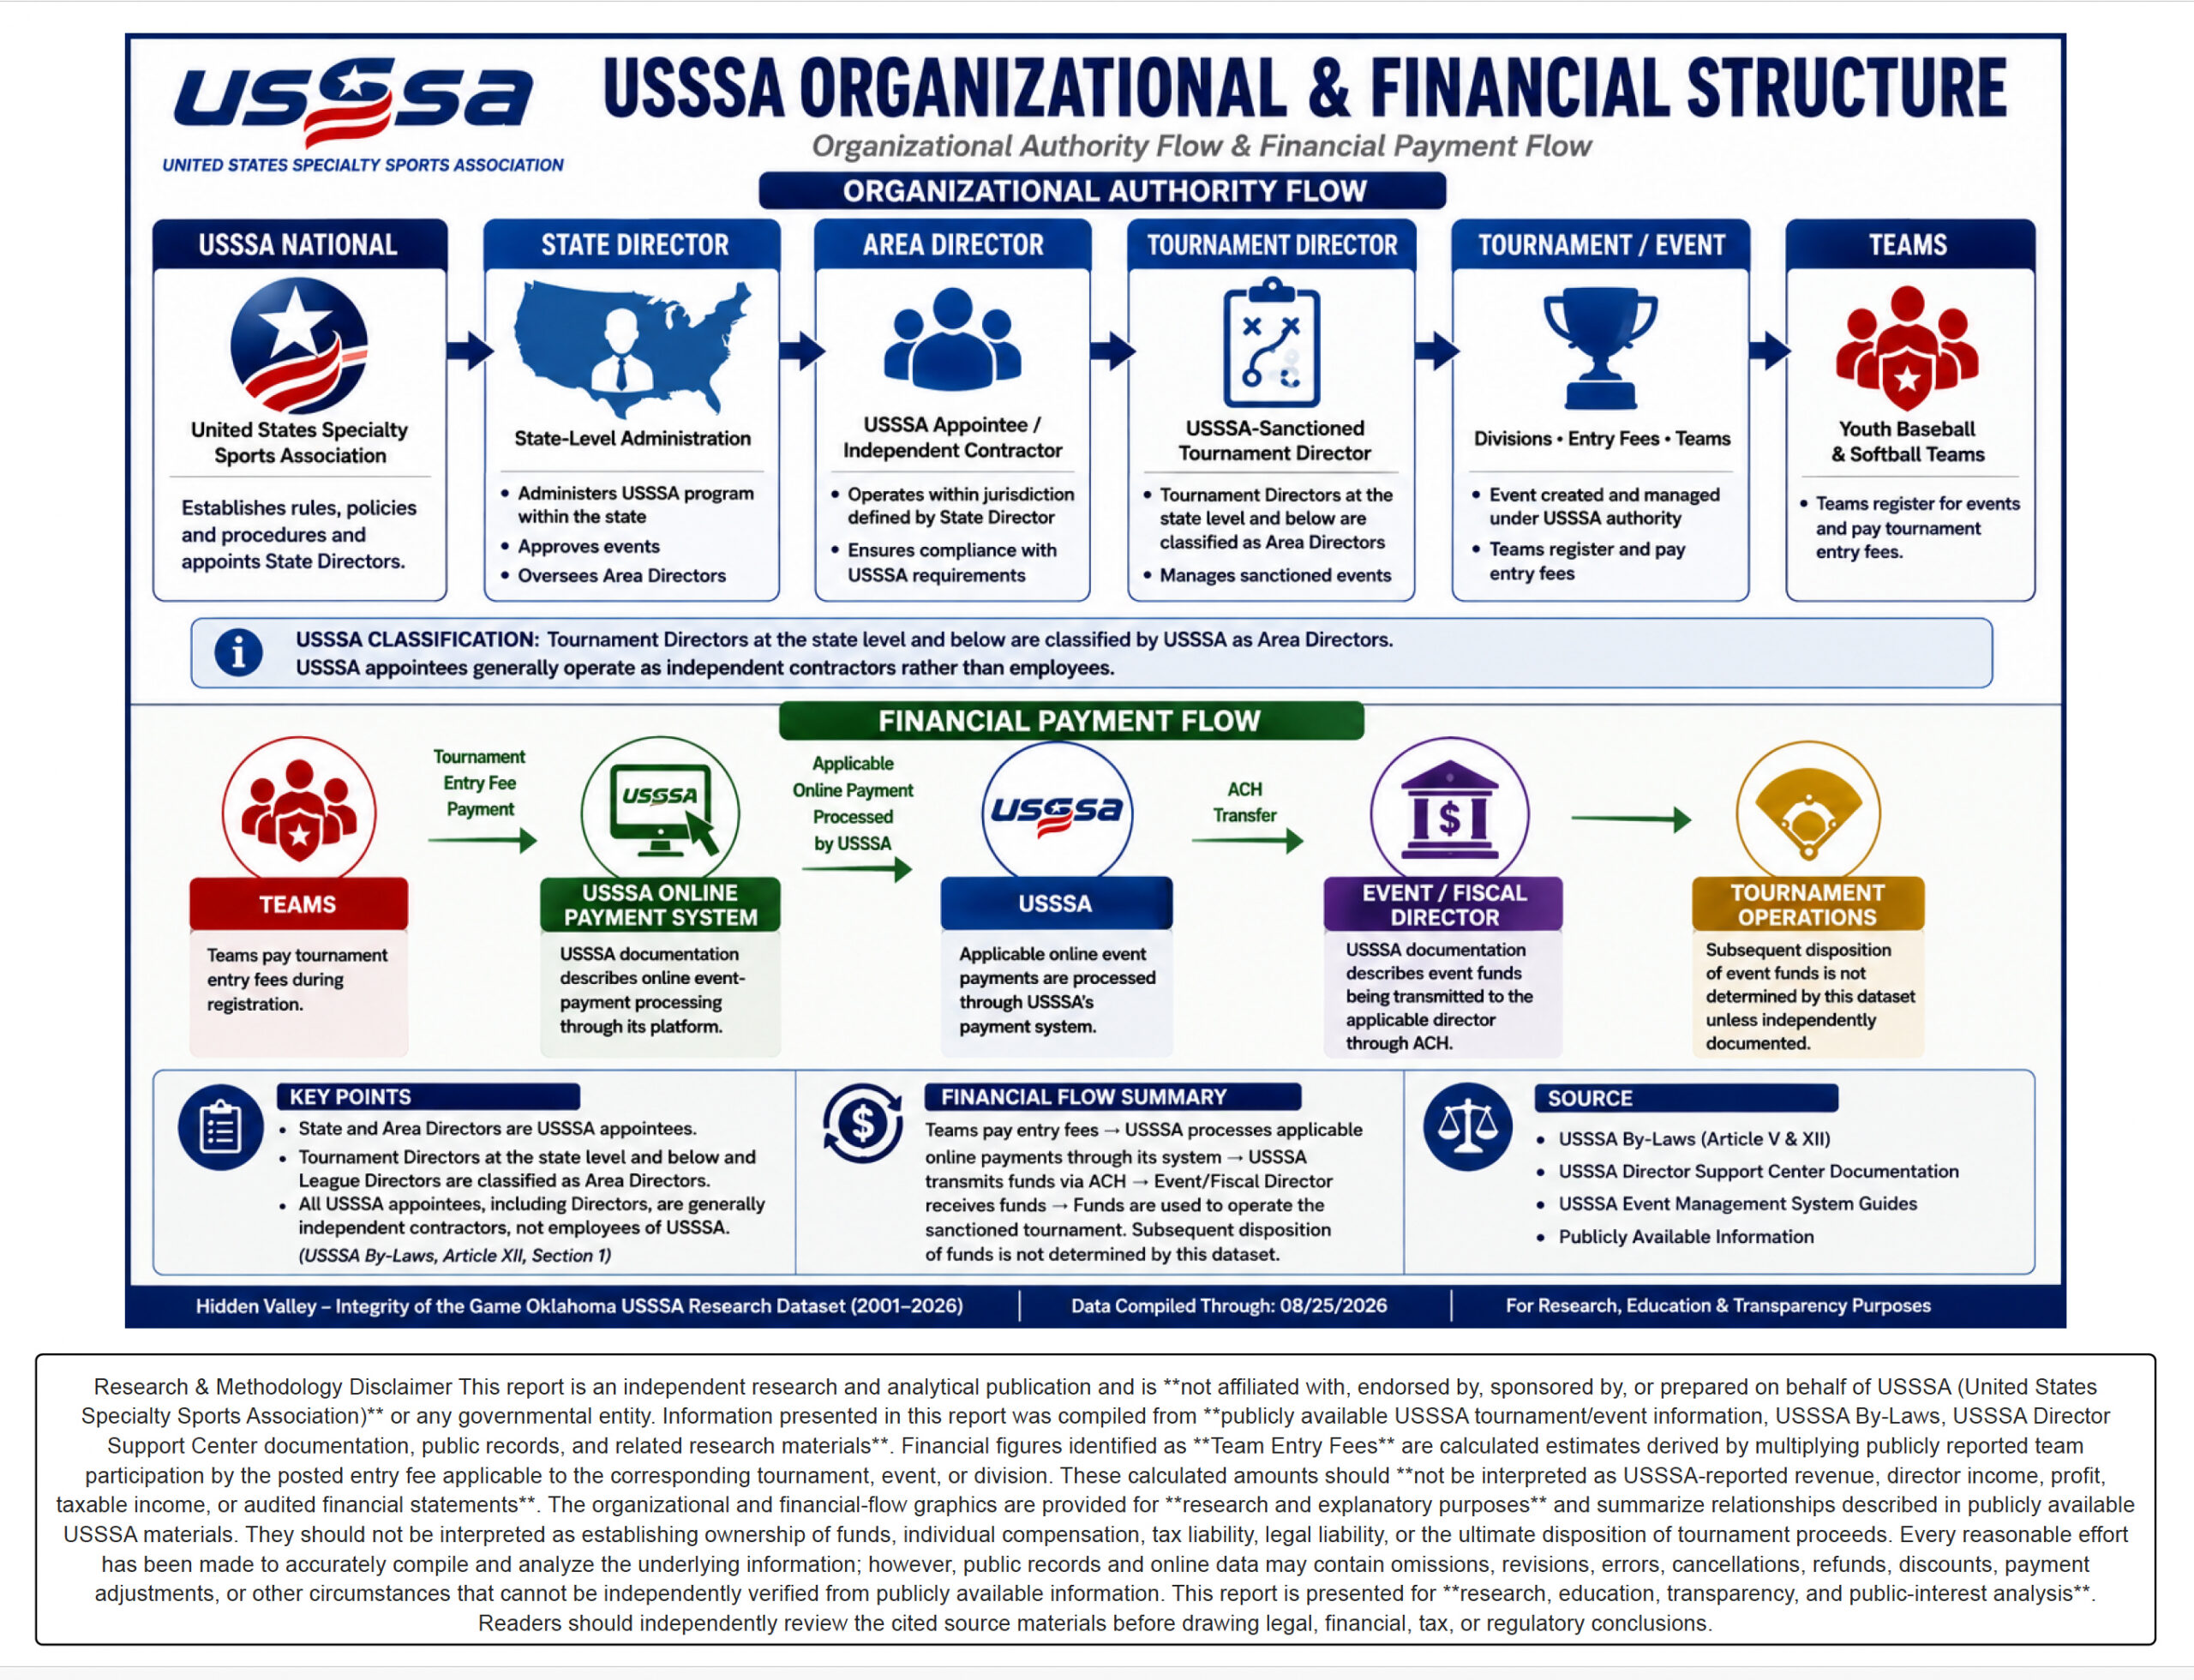
Research context: Calculated Team Entry Fees are estimates derived from publicly reported team participation and posted tournament entry fees. They are not represented as USSSA-reported aggregate revenue, director income, profit, taxable income or audited financial statements.

Director Activity Scorecard

Each figure begins at zero and counts to its final documented value.

$0Total Team Entry Fees
$0Baseball Team Entry Fees
$0Softball Team Entry Fees
0Teams
0Minimum Games Played
0Minimum Required Officials
0Divisions of Play
0Facilities
0Municipalities
0Counties
$0League Team Entry Fees
0League Teams

Updated Research Findings

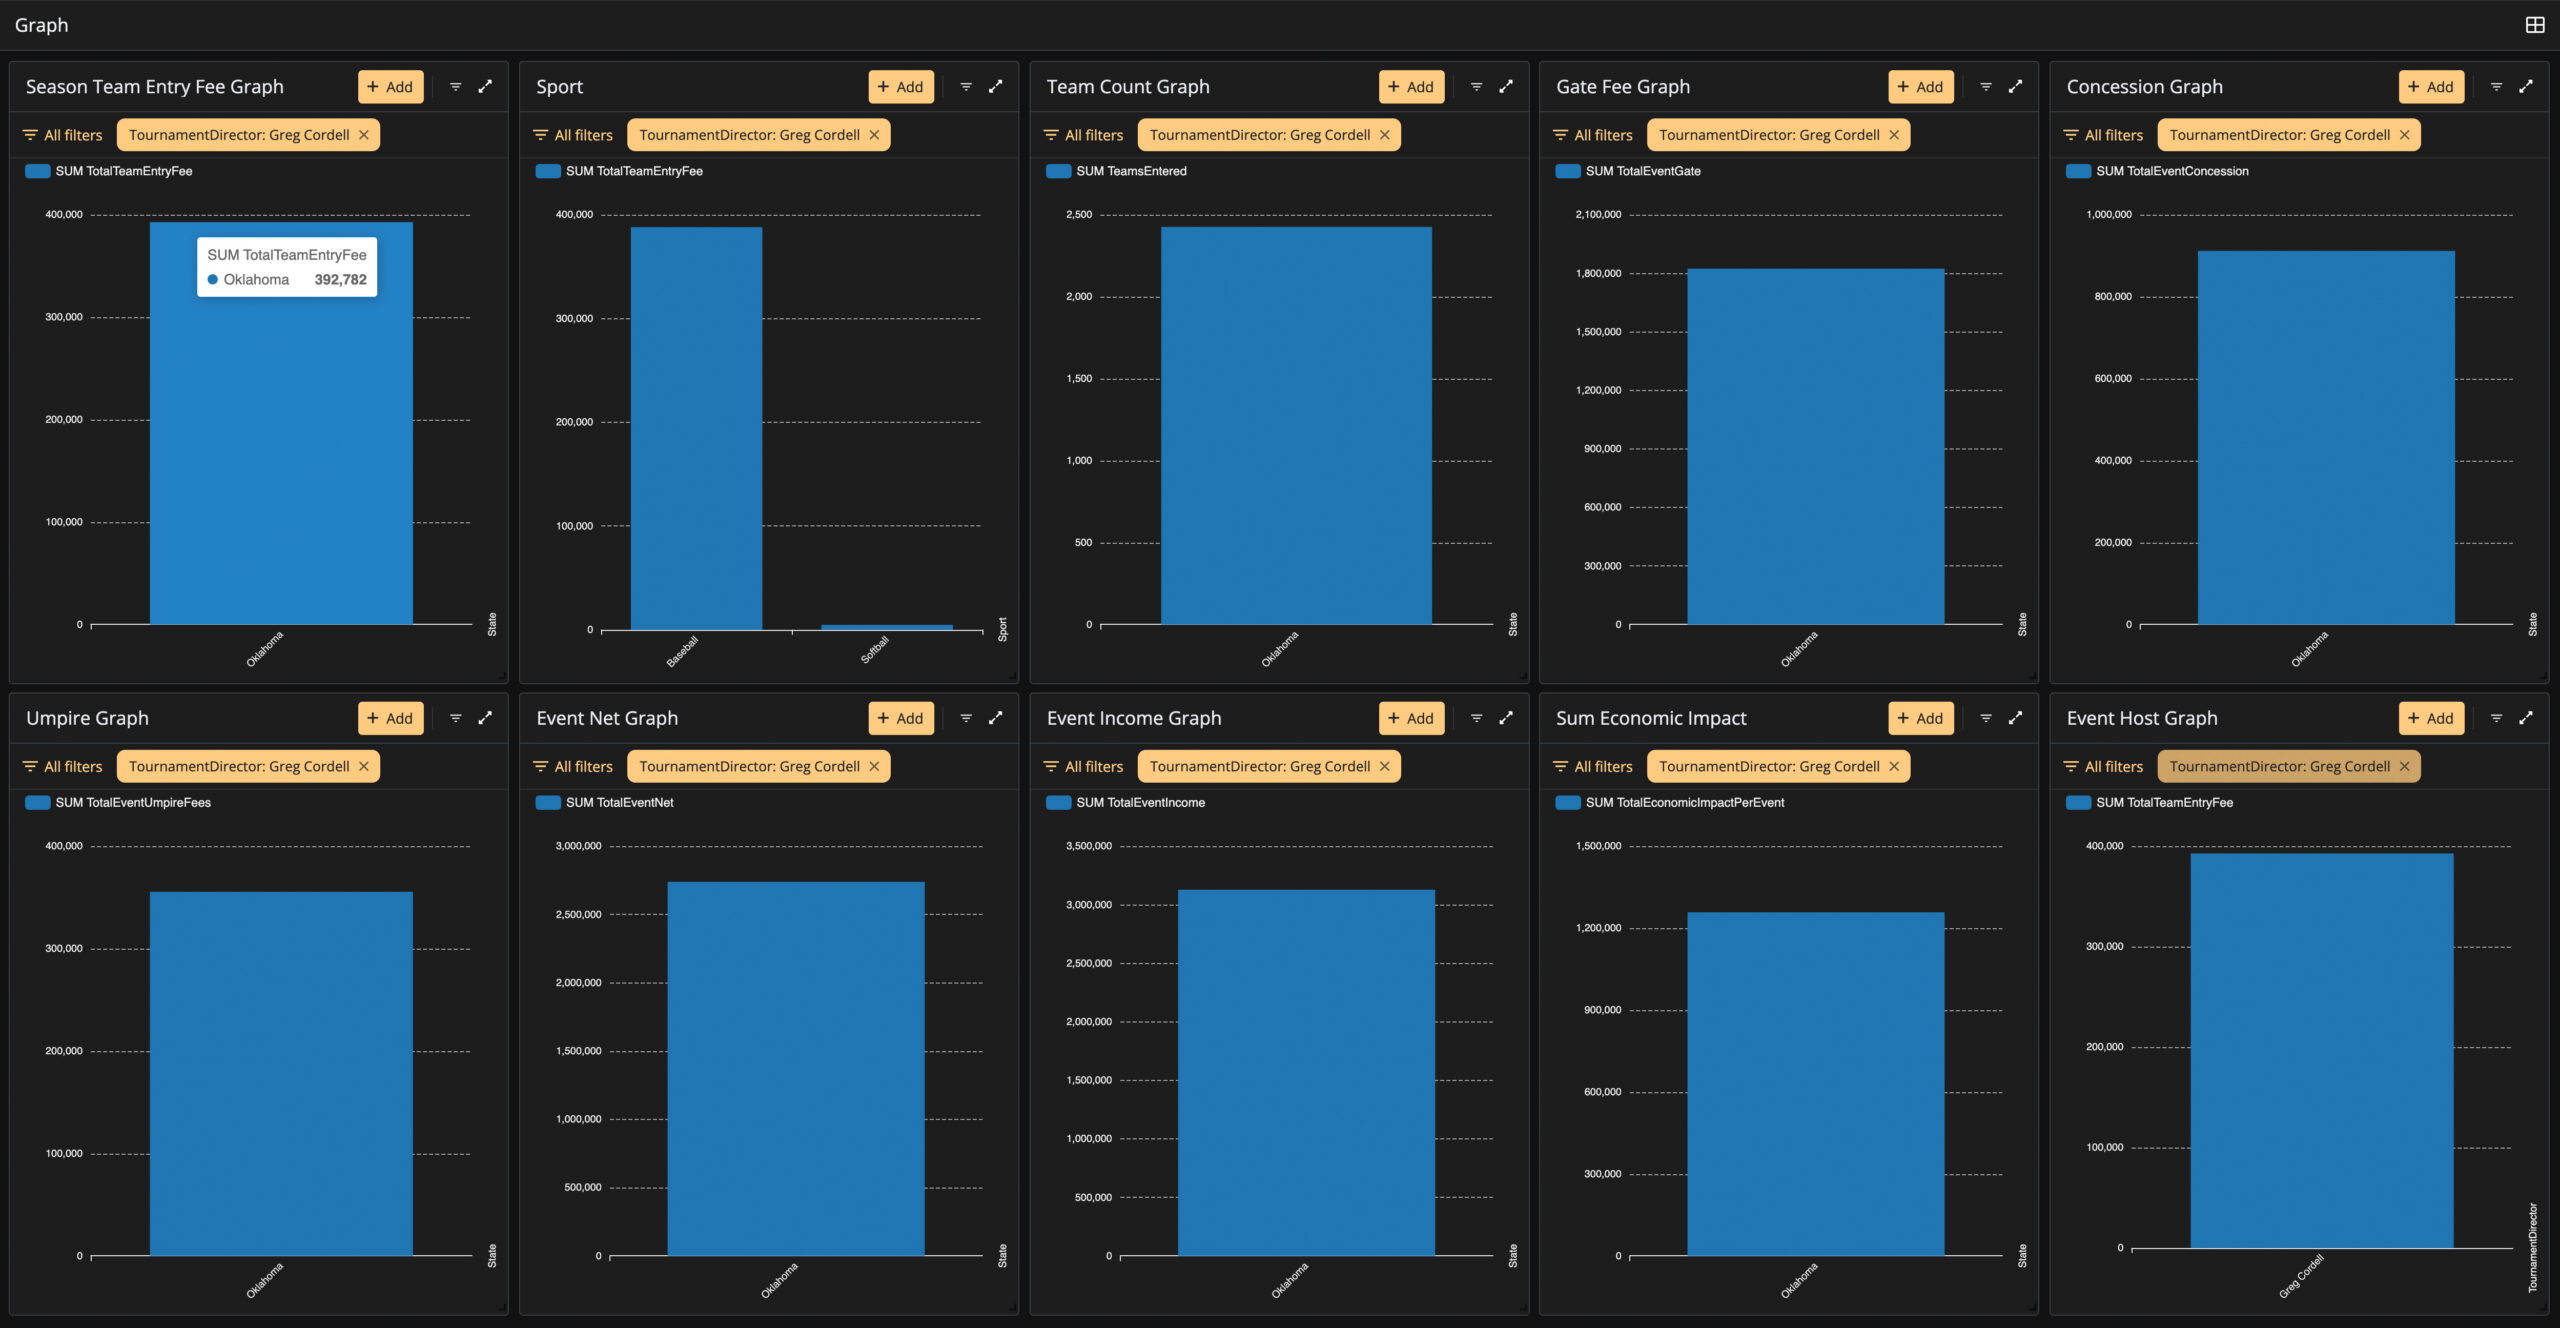
The current profile documents $392,782 in calculated team entry fees, 2,426 teams, 5,162 minimum games, 8,887 minimum required officials and 364 divisions, across six facilities, three municipalities and two counties.

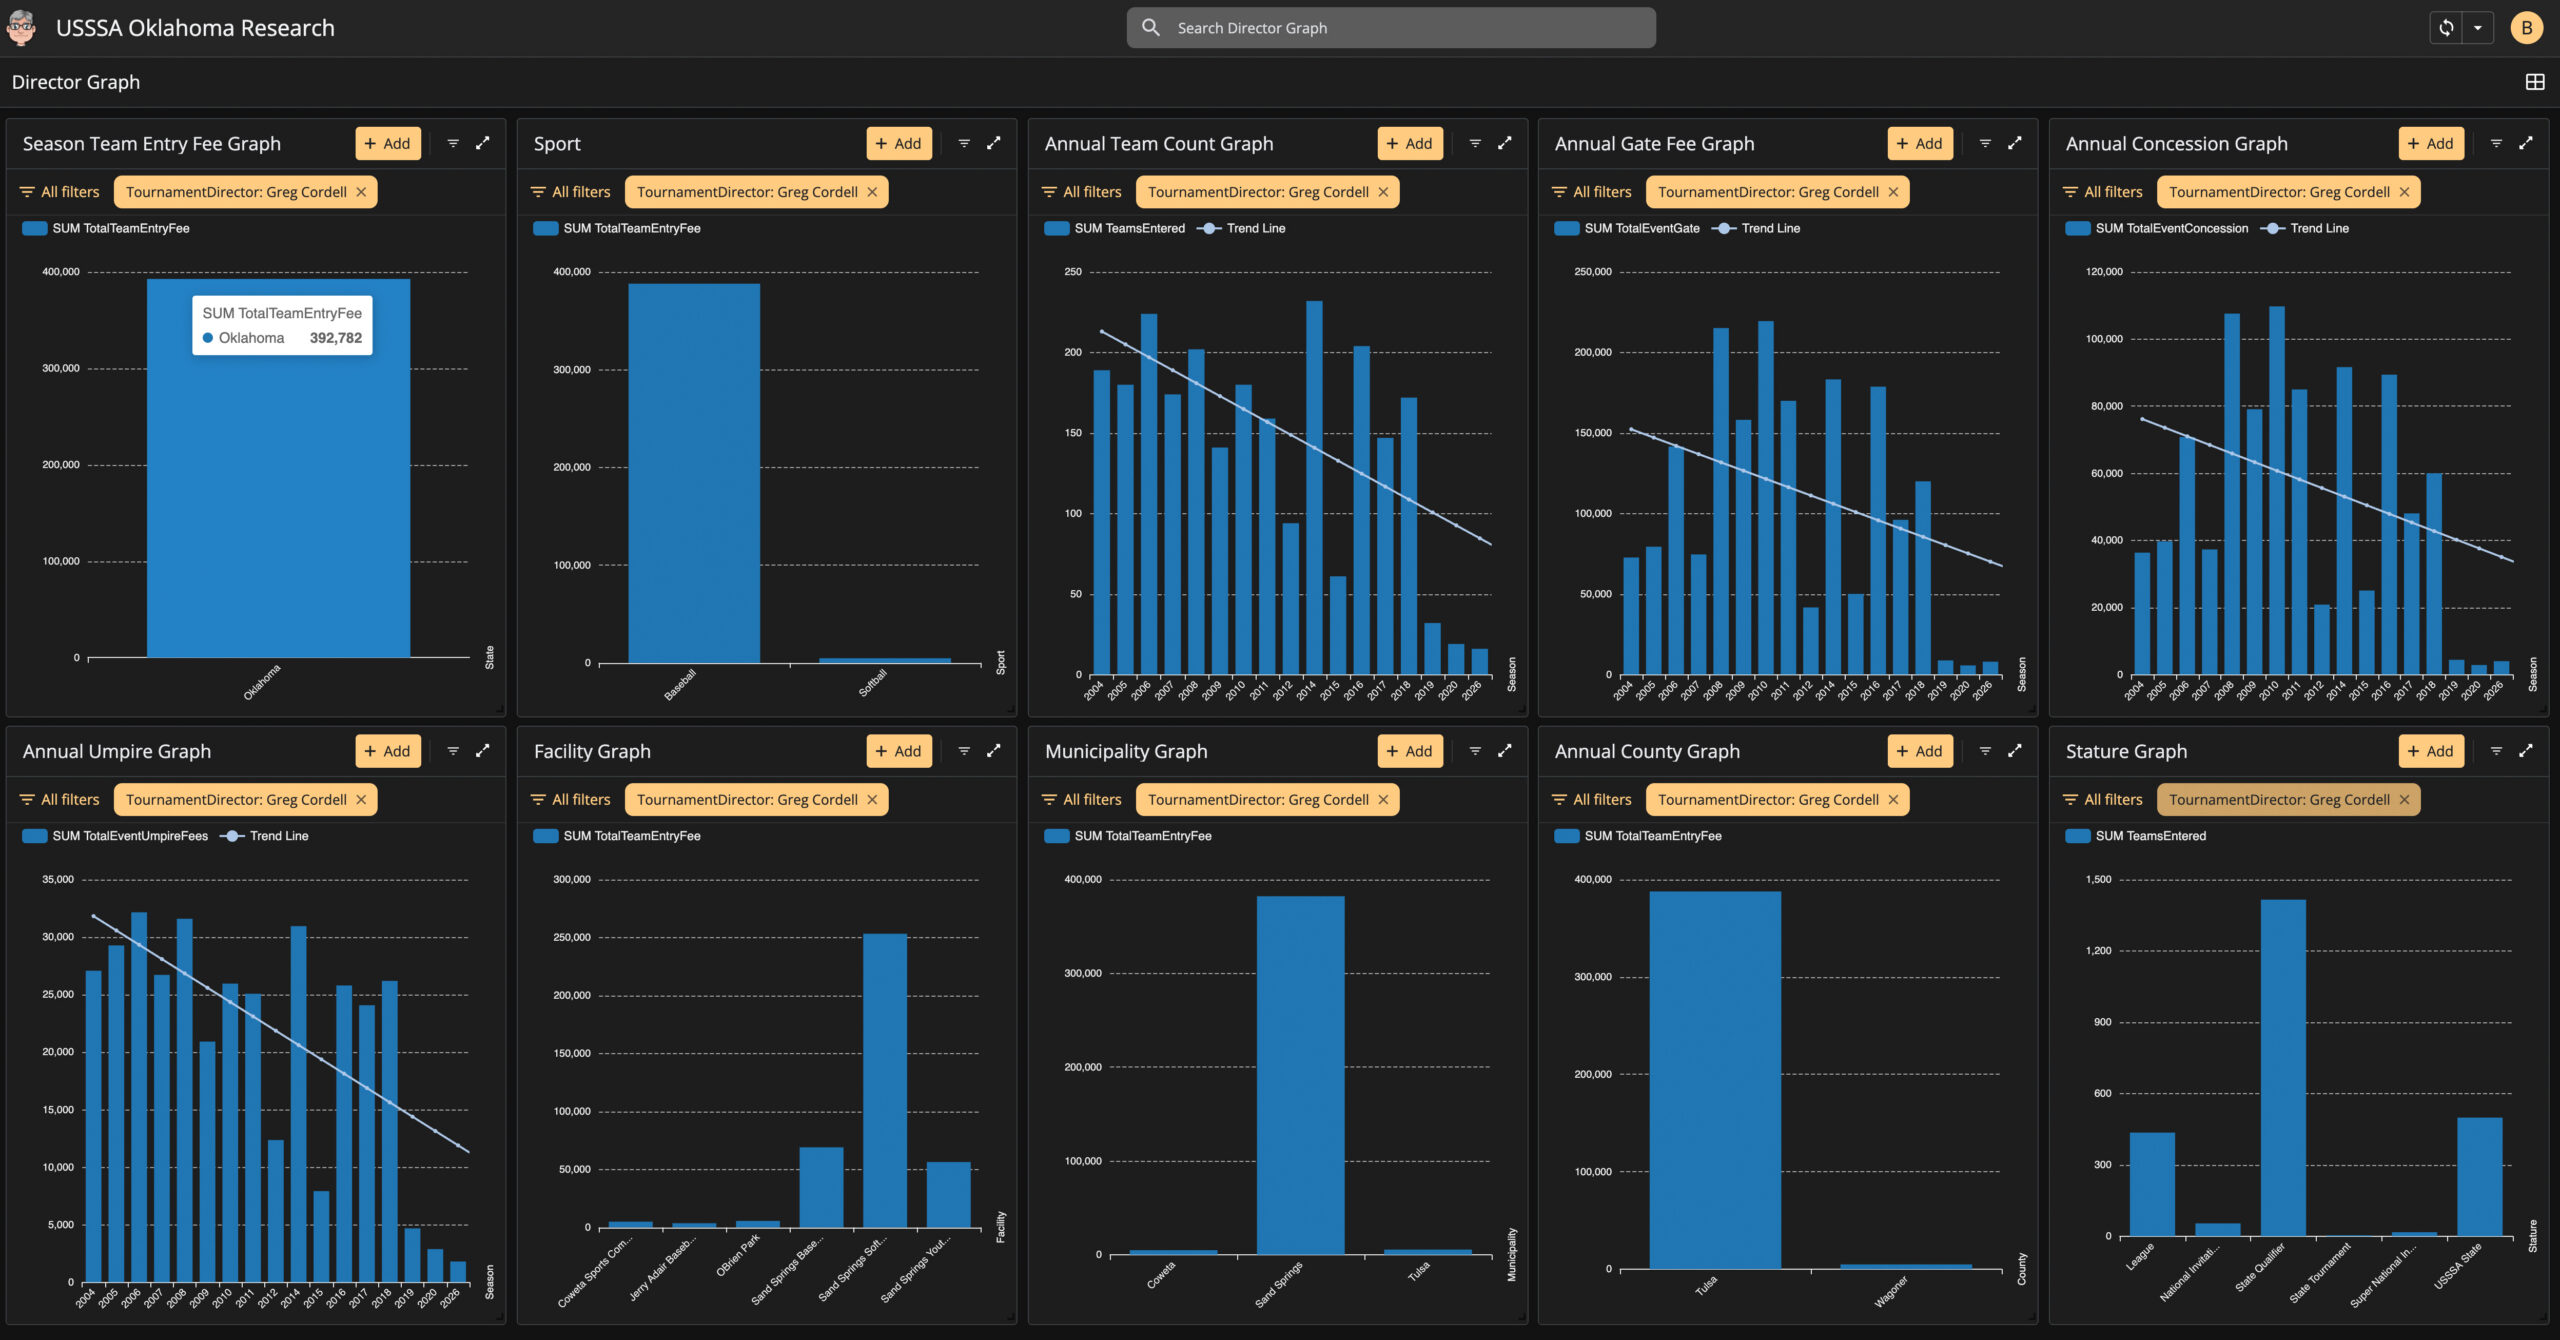
Baseball accounts for $388,057; softball accounts for $4,725. Sand Springs accounts for $382,311 of the municipality-level total.

Largest Facility Concentrations

Sand Springs Softball Complex — $253,306

Sand Springs Baseball Complex — $69,072

Sand Springs Youth Baseball — $56,363

Combined: $378,741

Calculated Team Entry Fees — Animated Graphs

Each graph begins at zero and grows to its final source values when entering view.

Calculated Team Entry Fees by Season

By Municipality

By County

By Facility

Source & Methodology

Data was compiled from publicly available USSSA tournament and event information for Oklahoma. Calculated Team Entry Fees are derived by multiplying participating teams by the publicly posted entry fee applicable to the event or division. These figures should not be interpreted as USSSA-reported aggregate revenue, director income, profit, taxable income, audited financial statements, ownership of funds, individual compensation, tax liability, legal liability or the ultimate disposition of tournament proceeds.